 Audrey
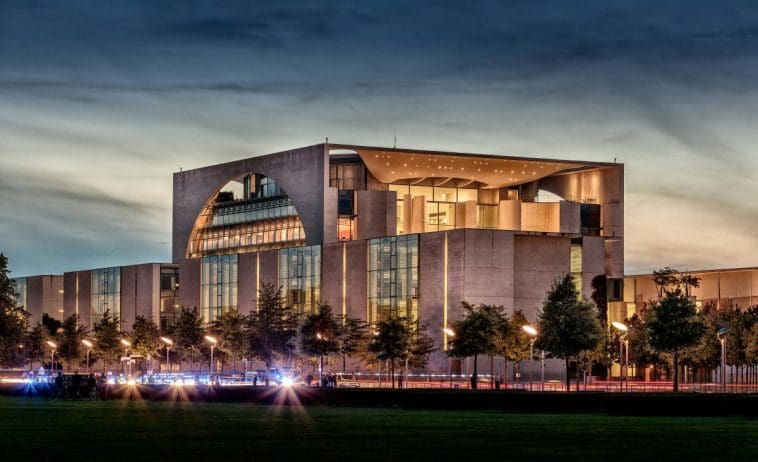
You notice the difference the moment a building stops behaving like a standard office or apartment. Specialty properties carry custom systems and finishes that refuse to sit quietly on a 39-year schedule. That resistance is where cost segregation creates breathing room for owners.
Specialty Properties Carry Components the Tax Code Already Treats Differently
The IRS’s February 2025 Cost Segregation Audit Technique Guide lists 13 principal elements of a quality study, including a clear legal analysis separating personal property from structural components and a full reconciliation to actual costs. Specialty buildings such as hospitals, data centers and manufacturing plants routinely contain items with far shorter useful lives than the shell that houses them.
Owners comparing cost segregation providers for Airbnb hosts often start with short-term rentals because furniture and site improvements appear in large quantities. The same logic scales to hotels, medical offices, or production facilities. On a Journal of Accountancy podcast, Brian Lovett described the expectation of a large first-year deduction after a cost segregation review as part of the fabric of the real estate industry.
Permanent Bonus Depreciation Changes the Math for New Specialty Projects
For property acquired after January 19, 2025, the One Big Beautiful Bill Act permanently restored 100 percent bonus depreciation for assets with recovery periods of 20 years or less. That turns the portion of basis a study reclassifies into an immediate deduction.
Consider a hypothetical 200,000-square-foot manufacturing plant where about 80 percent of the area is integral to production. The new qualified production property rules can allow immediate expensing of that share, and cost segregation can still identify short-life components in the rest of the building.
Owners evaluating cost segregation providers for different property types look for firms that understand both the permanent bonus rules and the production-property election. The two interact on industrial and agricultural specialty assets.
Engineering Studies Separate What Wears Out From What Holds the Building Up
The Cost Segregation Audit Technique Guide favors detailed engineering approaches that start from actual cost records or documented estimates. These apply the Whiteco factors and functional-use tests to decide permanence.
Electrical distribution that powers specialized hospital equipment is treated differently from circuits that light corridors. Decorative lighting, process piping and certain land improvements can move to 5-, 7- or 15-year lives when the study documents how they are attached and used.
Unusual Buildings Create Both Design Impact and Distinct Depreciation Pools
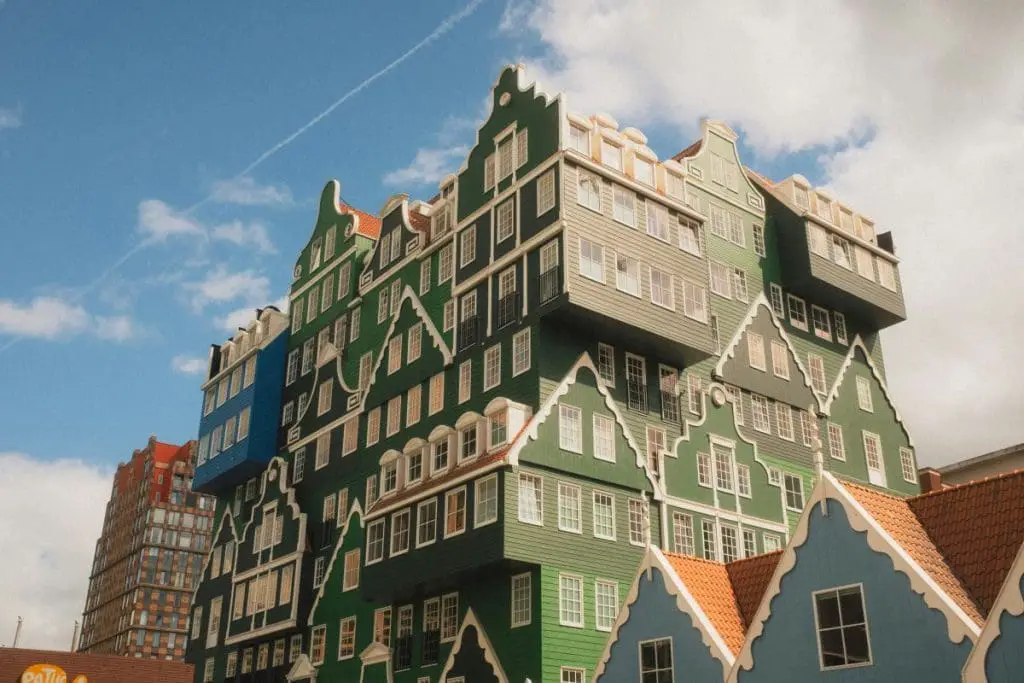
Structures that break conventional rules often pack non-standard materials and systems. Earlier coverage of the world’s strangest buildings shows how forms that defy gravity rely on custom structural elements along with specialized finishes, decorative elements, and unique site work. The specialized finishes, decorative elements, and site work (not the structural components themselves) frequently qualify for accelerated treatment once an engineer isolates them from the long-life shell.
A previous look at sustainable building materials and practices in unusual architecture underscores the point. Decorative, non-structural features made from materials like bamboo or recycled glass can sometimes fall into shorter-lived asset classes, while the same materials used structurally stay with the building.
Hotels, medical offices and data centers tend to show higher reclassification percentages than plain warehouses, because much of their cost sits in furniture, fixtures, dedicated HVAC and power systems that support equipment rather than the building itself.
Owners Still Need Defensible Studies When the Building Is Unusual
Quality remains the filter. The Audit Technique Guide stresses that a study must be prepared by someone with relevant expertise. It must explain the legal basis for each classification and reconcile every dollar to the total cost.
Specialty properties raise the stakes because their custom systems rarely match standard asset lists, so owners look for providers who document site visits, load studies and the functional purpose of each system.
A short list of elements that commonly move on specialty properties includes:
- Dedicated electrical and plumbing that serve equipment rather than the building
- Removable finishes, flooring, and millwork in hotels and medical suites
- Raised floors, cooling towers, and power distribution in data centers
- Process piping and specialty HVAC in manufacturing or agricultural buildings
- Site paving, landscaping, and exterior lighting that support operations but are not structural
Planning Windows Remain Open for Properties Placed in Service This Year and Next
Acquisition and placed-in-service dates still control eligibility. Property acquired before January 20, 2025, stays under the older bonus rates, and the qualified production property election applies only to property placed in service before January 1, 2031.
Owners who already hold specialty assets can often file a change in accounting method to claim missed depreciation without amending prior returns.
If you own or are evaluating a specialty property, the next step is a documented engineering review that maps its components to the categories the IRS already accepts.